EXECUTIVE PROPERTY BRIEF
Yongsan:
Two Landmark Opportunities
A decision-ready introduction to The Parkside Seoul, Eterno Yongsan and the Korean acquisition framework for international buyers.
The decision in one page
Both opportunities are concentrated in the same Yongsan transformation story, but they express it very differently: one is a large mixed-use ecosystem; the other is an ultra-private trophy residence.
Lease a Korean apartment—condo-style housing—before any later ownership decision.
- Korean apartment: proposed 10-year private-rental structure
- Year-ten sale conversion reported as a working plan; binding right unverified*
- Officetel: separate ownership product within the mixed-use project
- Rosewood Seoul, retail, work and cultural program
Best suited to a buyer prioritizing a broad amenity ecosystem and long-term optionality over immediate apartment title.
Secure a rare, highly private residence during development.
- Apartment 102-901: KRW 20.0bn · $14,492,754*
- Officetel 201 duplex: KRW 25.0bn · $18,115,942*
- 10% initial deposit; interim payments every six months*
- Target move-in: October 2029*
Best suited to a buyer prioritizing scarcity, architecture and a defined unit—while accepting construction and staged-payment risk.
The exact Parkside apartment purchase mechanism, all payment dates, unit specifications and Eterno completion terms have not yet been reviewed against executed contract documents.
“Apartment” does not mean the same thing in Korea and the United States.
In Korea, apartment describes a residential building category. It does not tell you whether the unit is owned or rented. For an individually owned Korean apartment, “condominium unit” is the closest U.S. shorthand. The Parkside’s proposed ten-year route, however, begins as a lease—not ownership.
Korean apartment (아파트)
Closest U.S. shorthand: condominium unitA Korean legal/building category for multi-family housing with five or more residential floors—not a statement that the unit is rented. When sold separately, the U.S. mental model is an individually owned condo unit with rights in shared parts.
Condominium / condo
An ownership form in U.S. usageUse “condominium unit” to explain an individually owned Korean apartment unit. It is an analogy, not the Korean statutory product name; a Korean apartment can also be held and operated as rental housing.
Rental / lease (임대·임대차)
Occupancy without titleThe tenant receives a contractual right to occupy. The deposit and rent do not normally create ownership equity, and the tenant is not the registered owner during the lease.
10-year private rental
Long-term rental in a condo-style buildingThis is closer to leasing a residence for a long period than buying a U.S. condo. It is not “rent-to-own” unless the final contract grants an enforceable purchase option and clearly states eligibility, timing and price mechanics.
Lease, sale conversion and presale are separate legal moments.
The buyer’s status changes only when the governing documents and title say it changes. Marketing language should never blur a tenancy, a future purchase opportunity and an existing ownership contract.
Sale conversion (분양전환)
Later conversion from rental to unit salesA rental unit may later be offered for sale, but ownership is not automatic at year ten. Confirm whether the tenant has a binding option, a preferential right, a negotiation opportunity or no guaranteed right—and how then-market value is established.
Presale / developer sale (분양)
Purchase contract before or during developmentThe buyer contracts to acquire a unit and usually pays in stages, with title registered after completion and closing. This is fundamentally different from an apartment lease.
Officetel (오피스텔)
No exact U.S. equivalentA business-facility / quasi-housing product commonly used as a residence. It may be separately owned like a condo, but legal use, VAT, lending, property tax and housing-count treatment can differ from an apartment.
Area language
Exclusive area ≠ marketed areaExclusive area is the private interior basis used for the unit; supplied or marketed area can include allocated common space. One pyeong equals about 3.3058 m². Always compare the same area basis.
Until the rental agreement and sale-conversion documents are reviewed, describe it as a proposed ten-year private rental with a reported future sale-conversion plan. A purchase at then-current market value would not lock today’s price, and rent paid during the lease should not be described as building equity unless the contract expressly provides otherwise.
Side-by-side
* Commercial information supplied by First Corporation / seller-side materials and subject to contract verification.
Building 102 · Unit 901
- Exclusive area
- 74 pyeong · 244.6 m²
- Marketed area
- 100 pyeong · 330.6 m²*
- Initial 10%
- KRW 2.0bn · $1,449,275
Unit 201 · Duplex
- Exclusive area
- 83 pyeong · 274.4 m²
- Configuration
- Duplex · details TBD
- Initial 10%
- KRW 2.5bn · $1,811,594
Prices in this report are preliminary guidance, not binding quotations. First Corporation currently estimates that approximately five Parkside Suites officetels and approximately four Eterno units remain; the Eterno unit-type mix has not been verified for this report. Inventory can change without notice and must be reconfirmed with the seller or showroom.
Current price sheets, availability, detailed plans, finishes, images and video are available for review inside the respective showrooms. Neither showroom accepts walk-ins: entry is by prior invitation with an agent in attendance. Eterno is handled on an especially private basis, so a pre-arranged showroom briefing is the appropriate verification route. Send your preferred date and time, plus an alternative, for coordination.
Planning rate: KRW 1,380/USD, not a live quote. Replace with the remitting bank’s execution rate before presentation or payment.
Why it matters
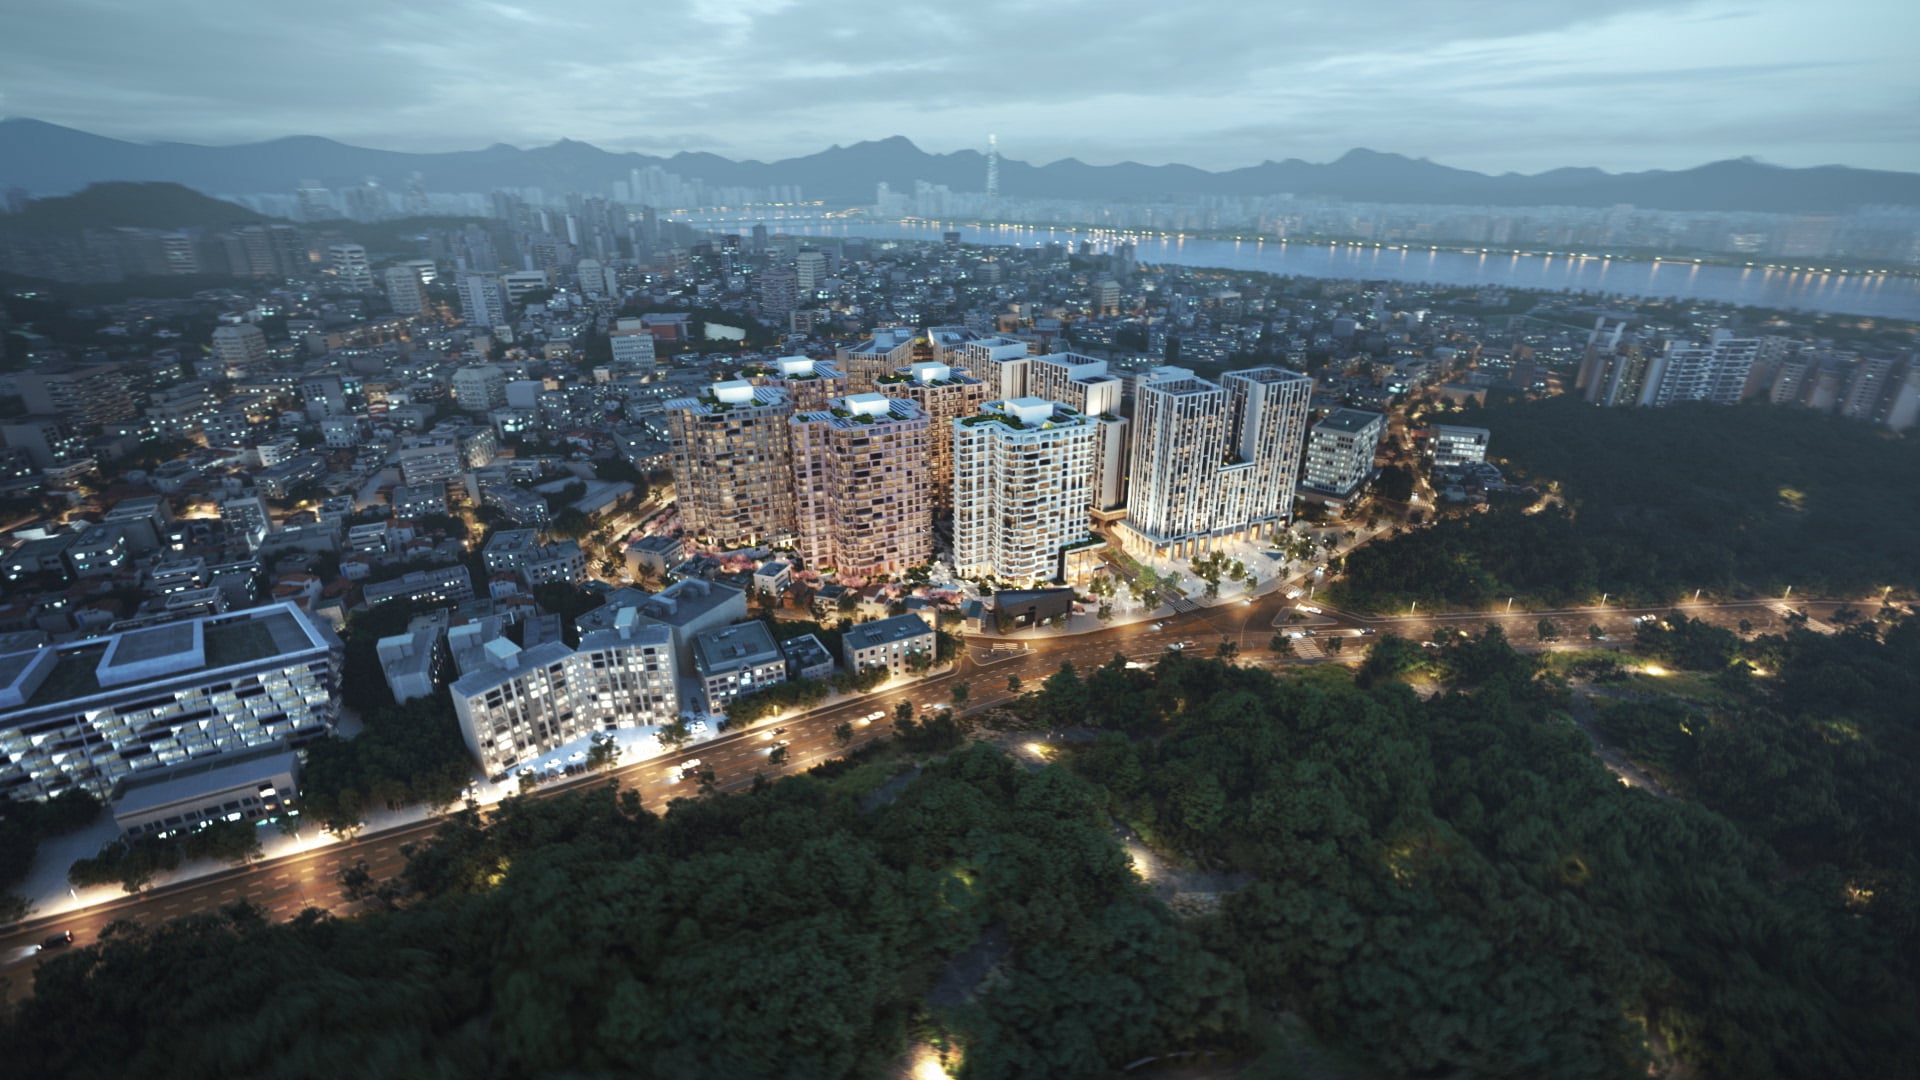
The former UN Command site sits immediately alongside the Yongsan Park transformation. The official program brings together Parkside Suites, apartments, Rosewood Seoul, a business center, retail, art and cultural space, The Parkside Way and UN Plaza.
The investment thesis is therefore tied not only to one building, but to the quality and execution of the entire place.
Questions the contract must answer
- Is the year-10 purchase a binding option, priority negotiation right, or merely an opportunity to bid?
- How is “market price” determined and who appoints the appraiser?
- What are rent, deposit, escalation, renewal and early-exit terms?
- Which amenities are included, separately charged or hotel-operated?
- Does the buyer’s intended use satisfy foreign-resident requirements?
Ten-year private-rental proposal*
The building type is comparable to condo-style housing, but the resident begins as a tenant without apartment title. Public reporting has described sale conversion after the rental period as a plan under review; the binding right, eligibility and valuation method remain contract questions.
Officetel ownership
Official and First Corporation materials describe 775 units across multiple room types. Legal use, residential registration, VAT, financing and management rules must be reviewed separately from an apartment purchase.
The proposition
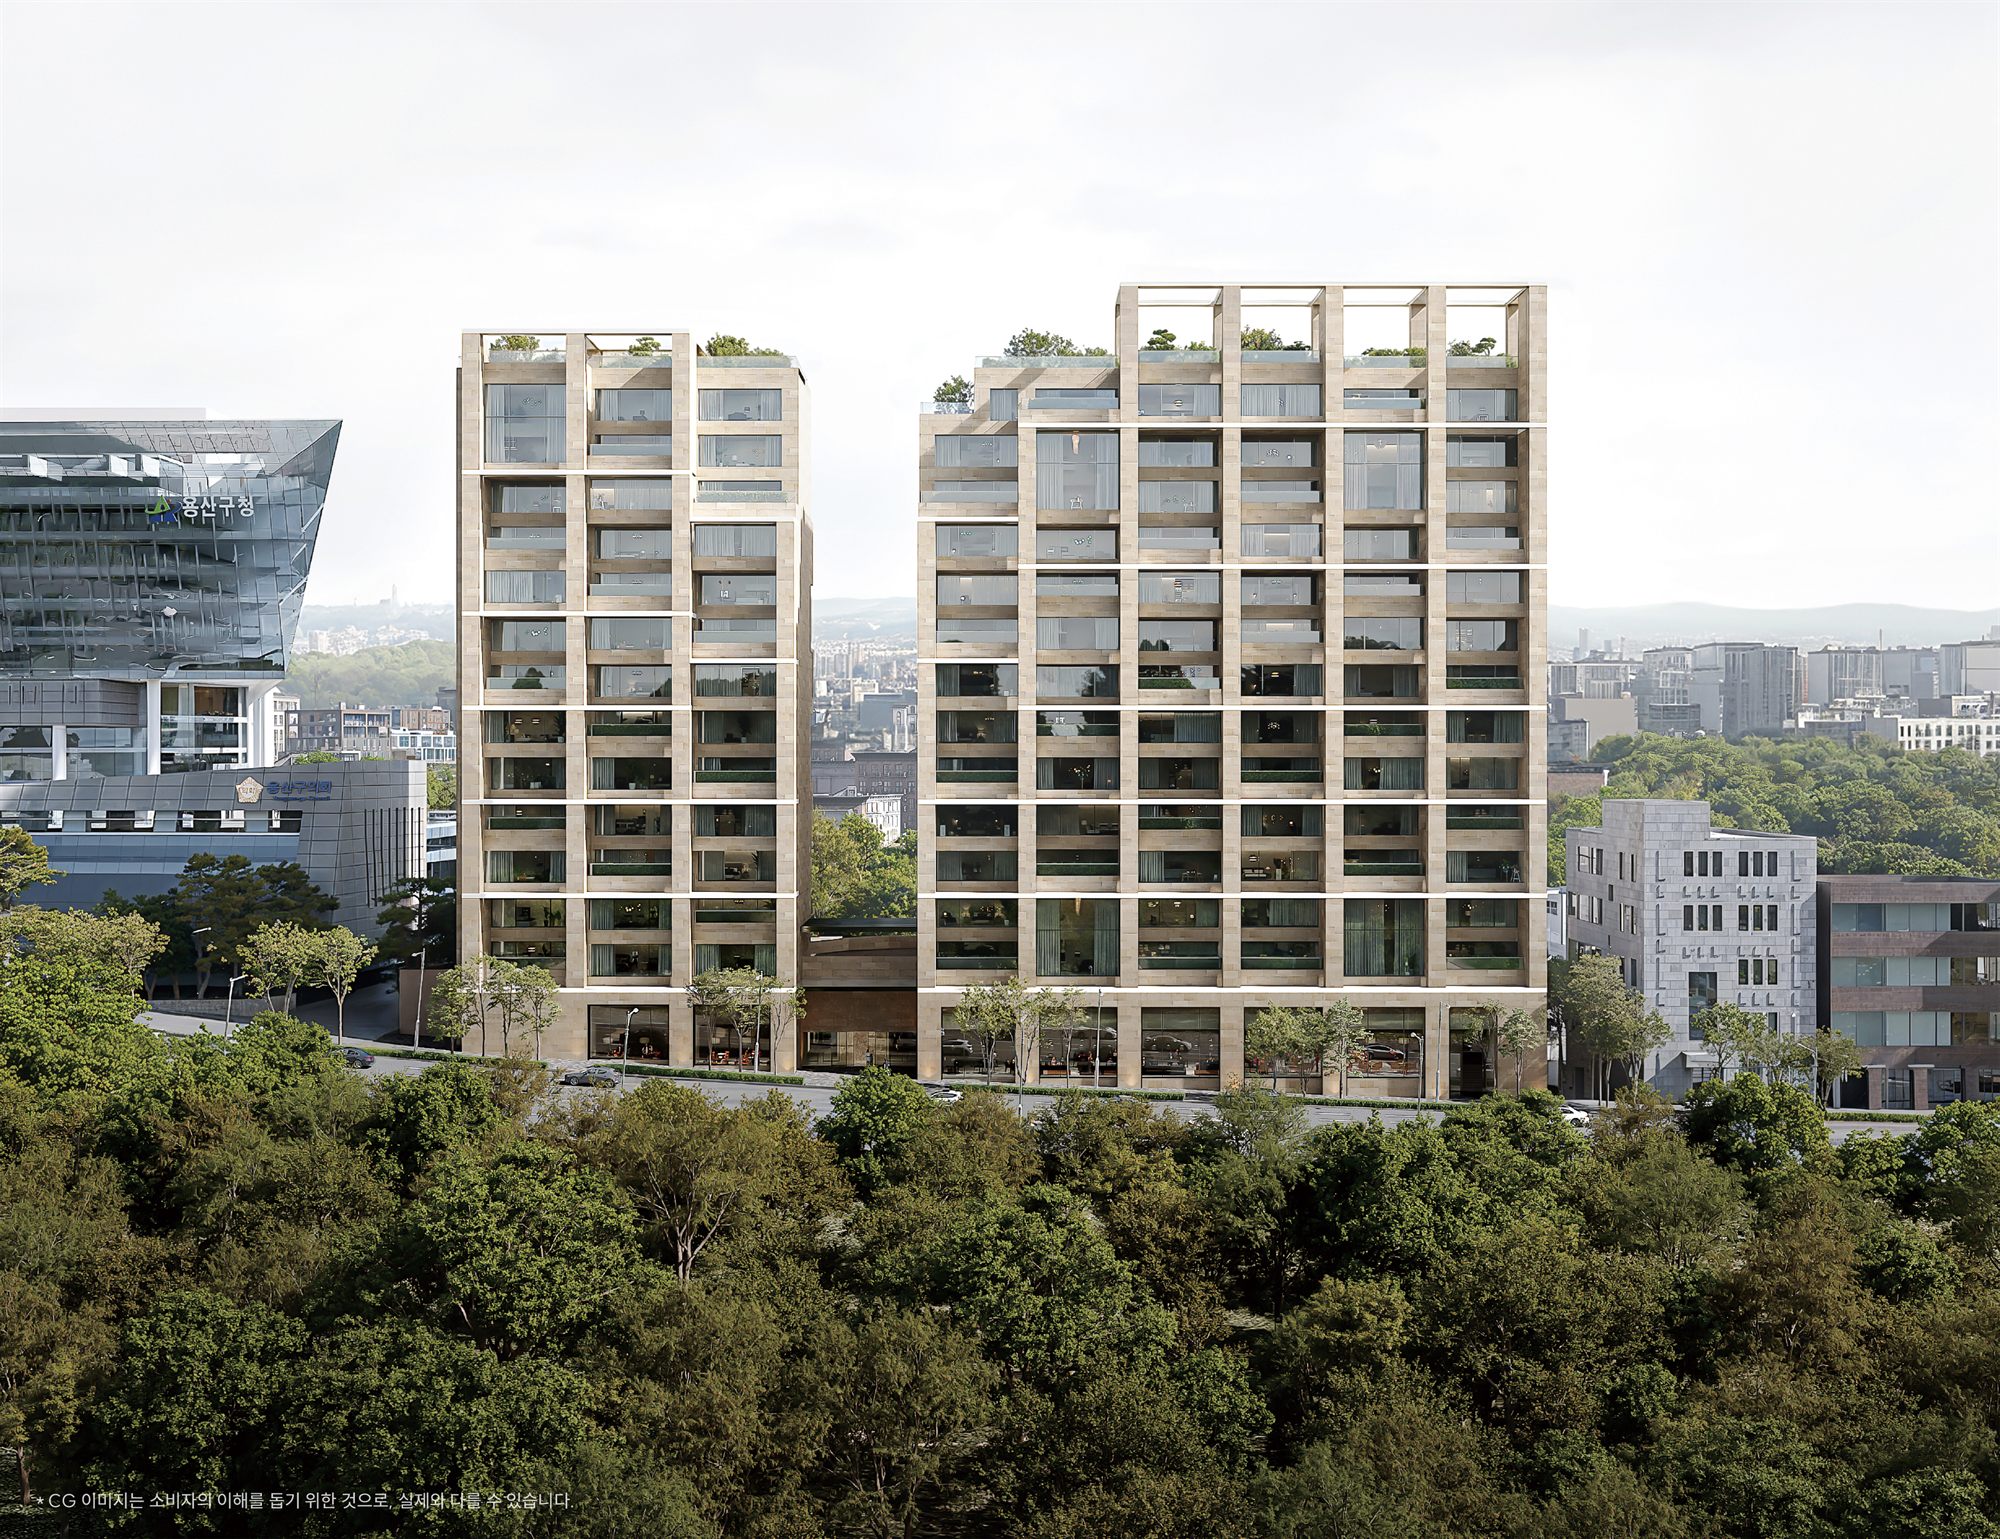
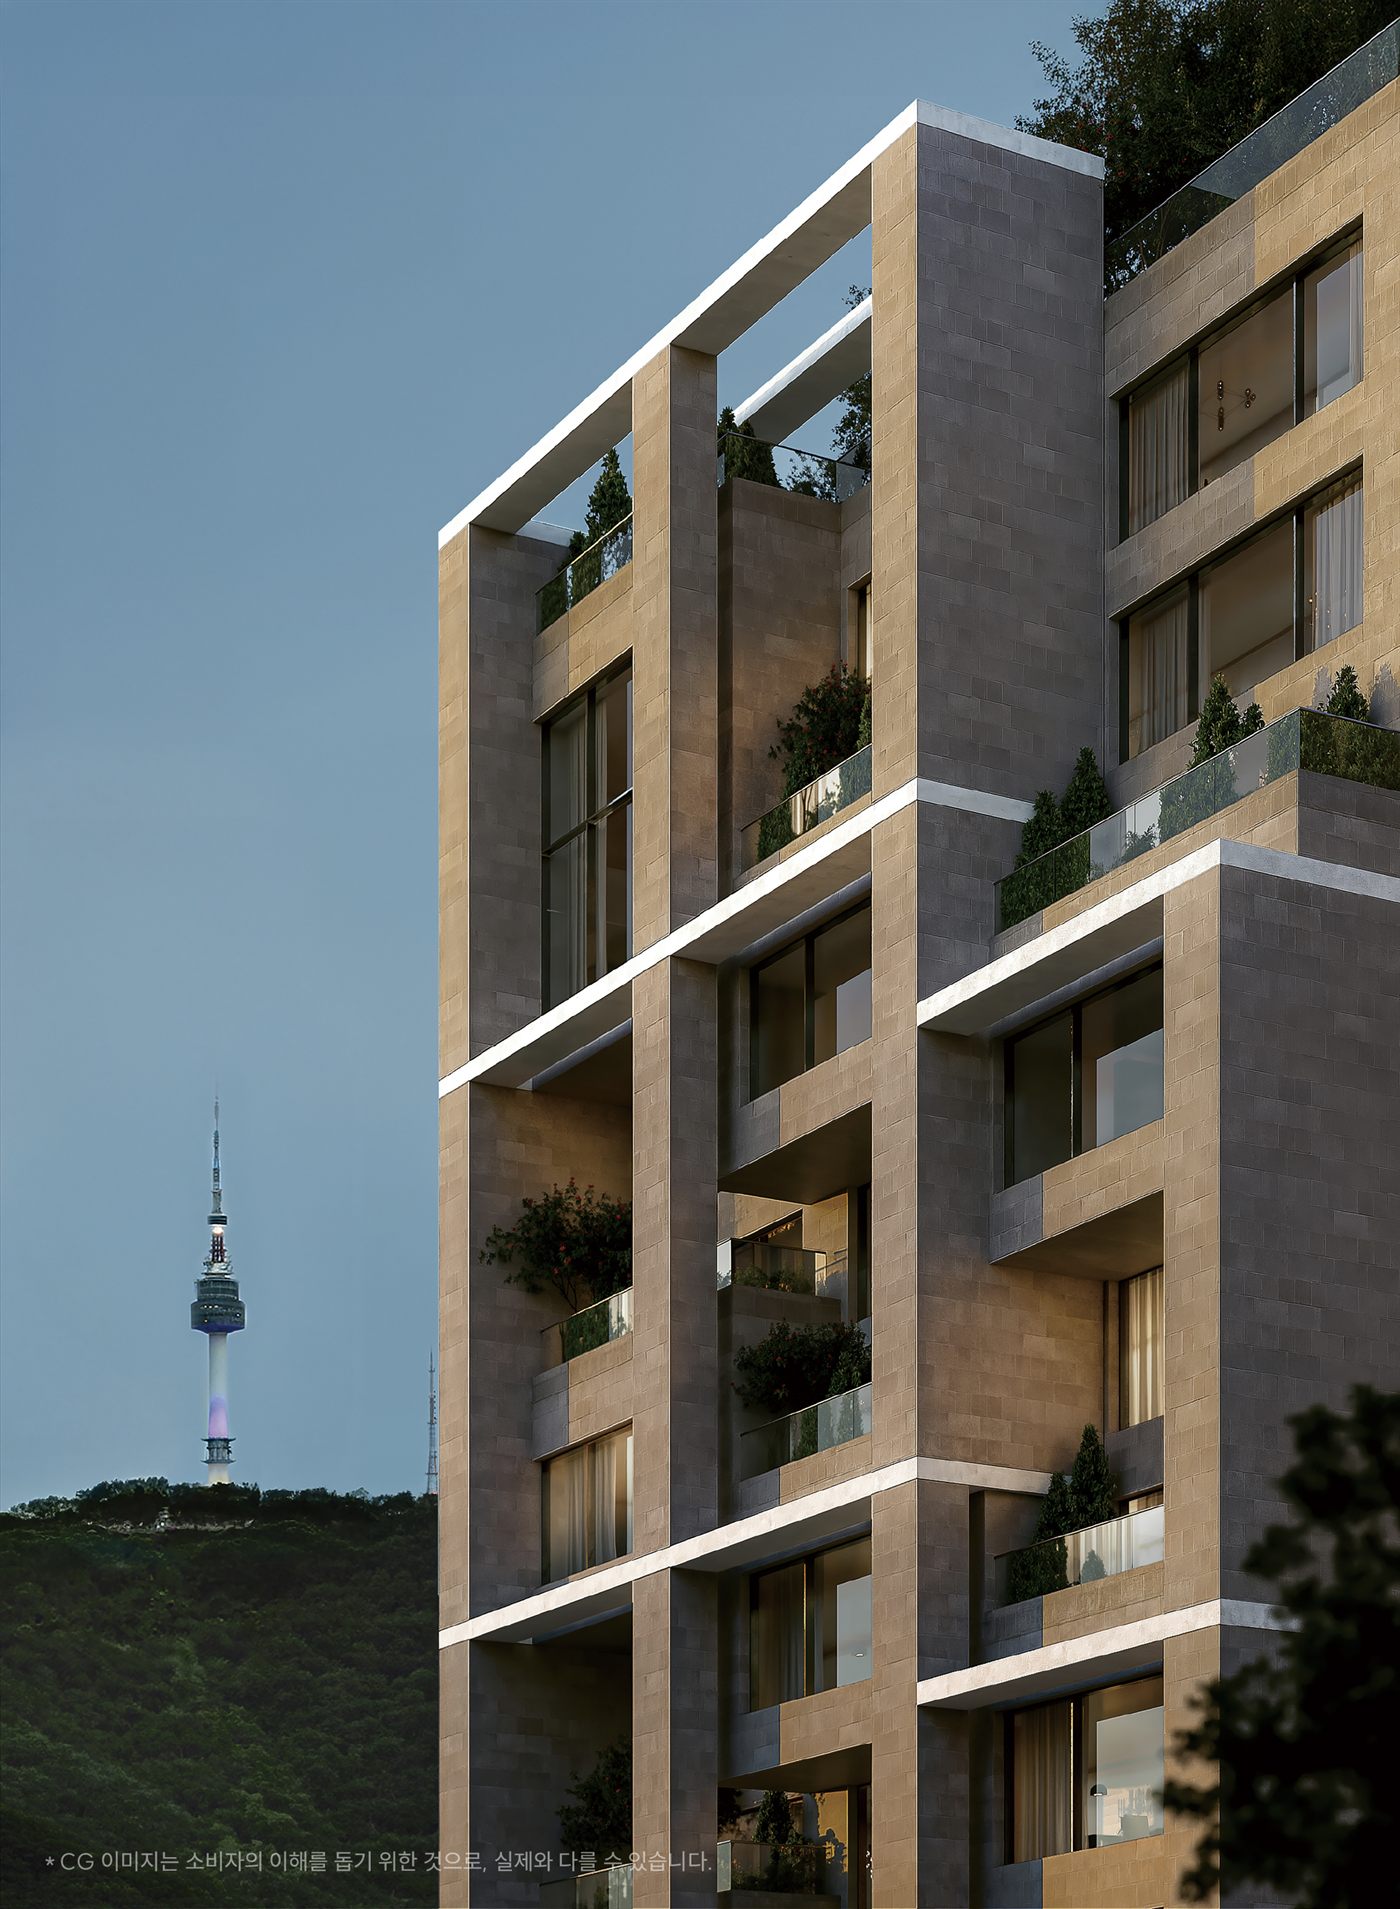
First Corporation’s current listing describes two buildings on the former Crown Hotel site, with 29 apartments and four officetels. Apartments are reported at approximately 74–135 pyeong exclusive area. The project continues the Eterno series with Pritzker Prize laureate Rafael Moneo involved in the design.
At this price level, the decision should be driven by the exact unit—view corridor, privacy, arrival sequence, parking, ceiling height, terrace, service area and finish schedule—not the brand alone.
Before paying the 10%
- Obtain the Korean contract, controlled English translation and all attachments.
- Confirm permit status, trust/escrow structure, land title and project finance security.
- Fix every interim-payment date, percentage and late-payment consequence.
- Confirm the completion definition, long-stop date and buyer remedies for delay.
- Verify whether VAT applies to unit 201 and what is included in the stated price.
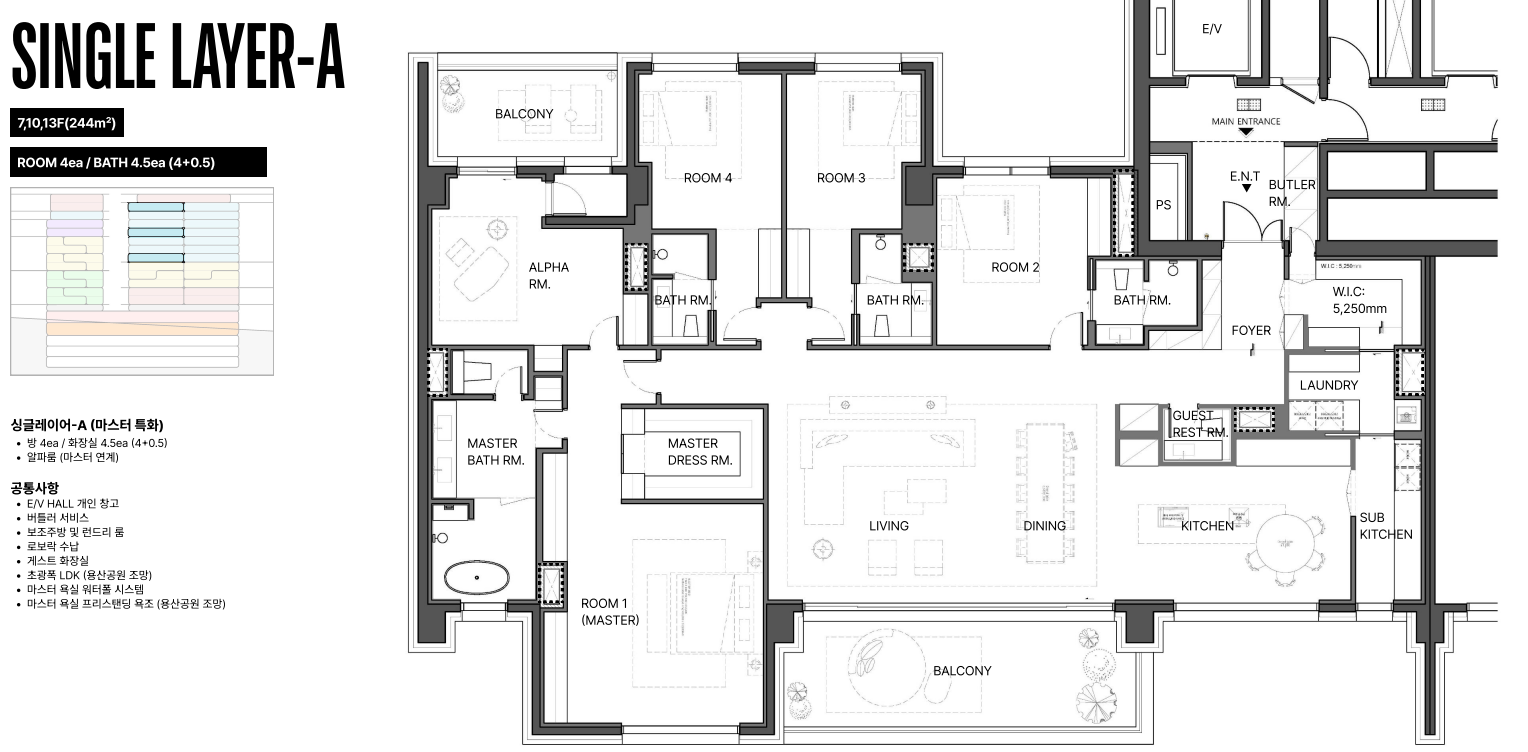
Single Layer-A · 244.6 m² exclusive
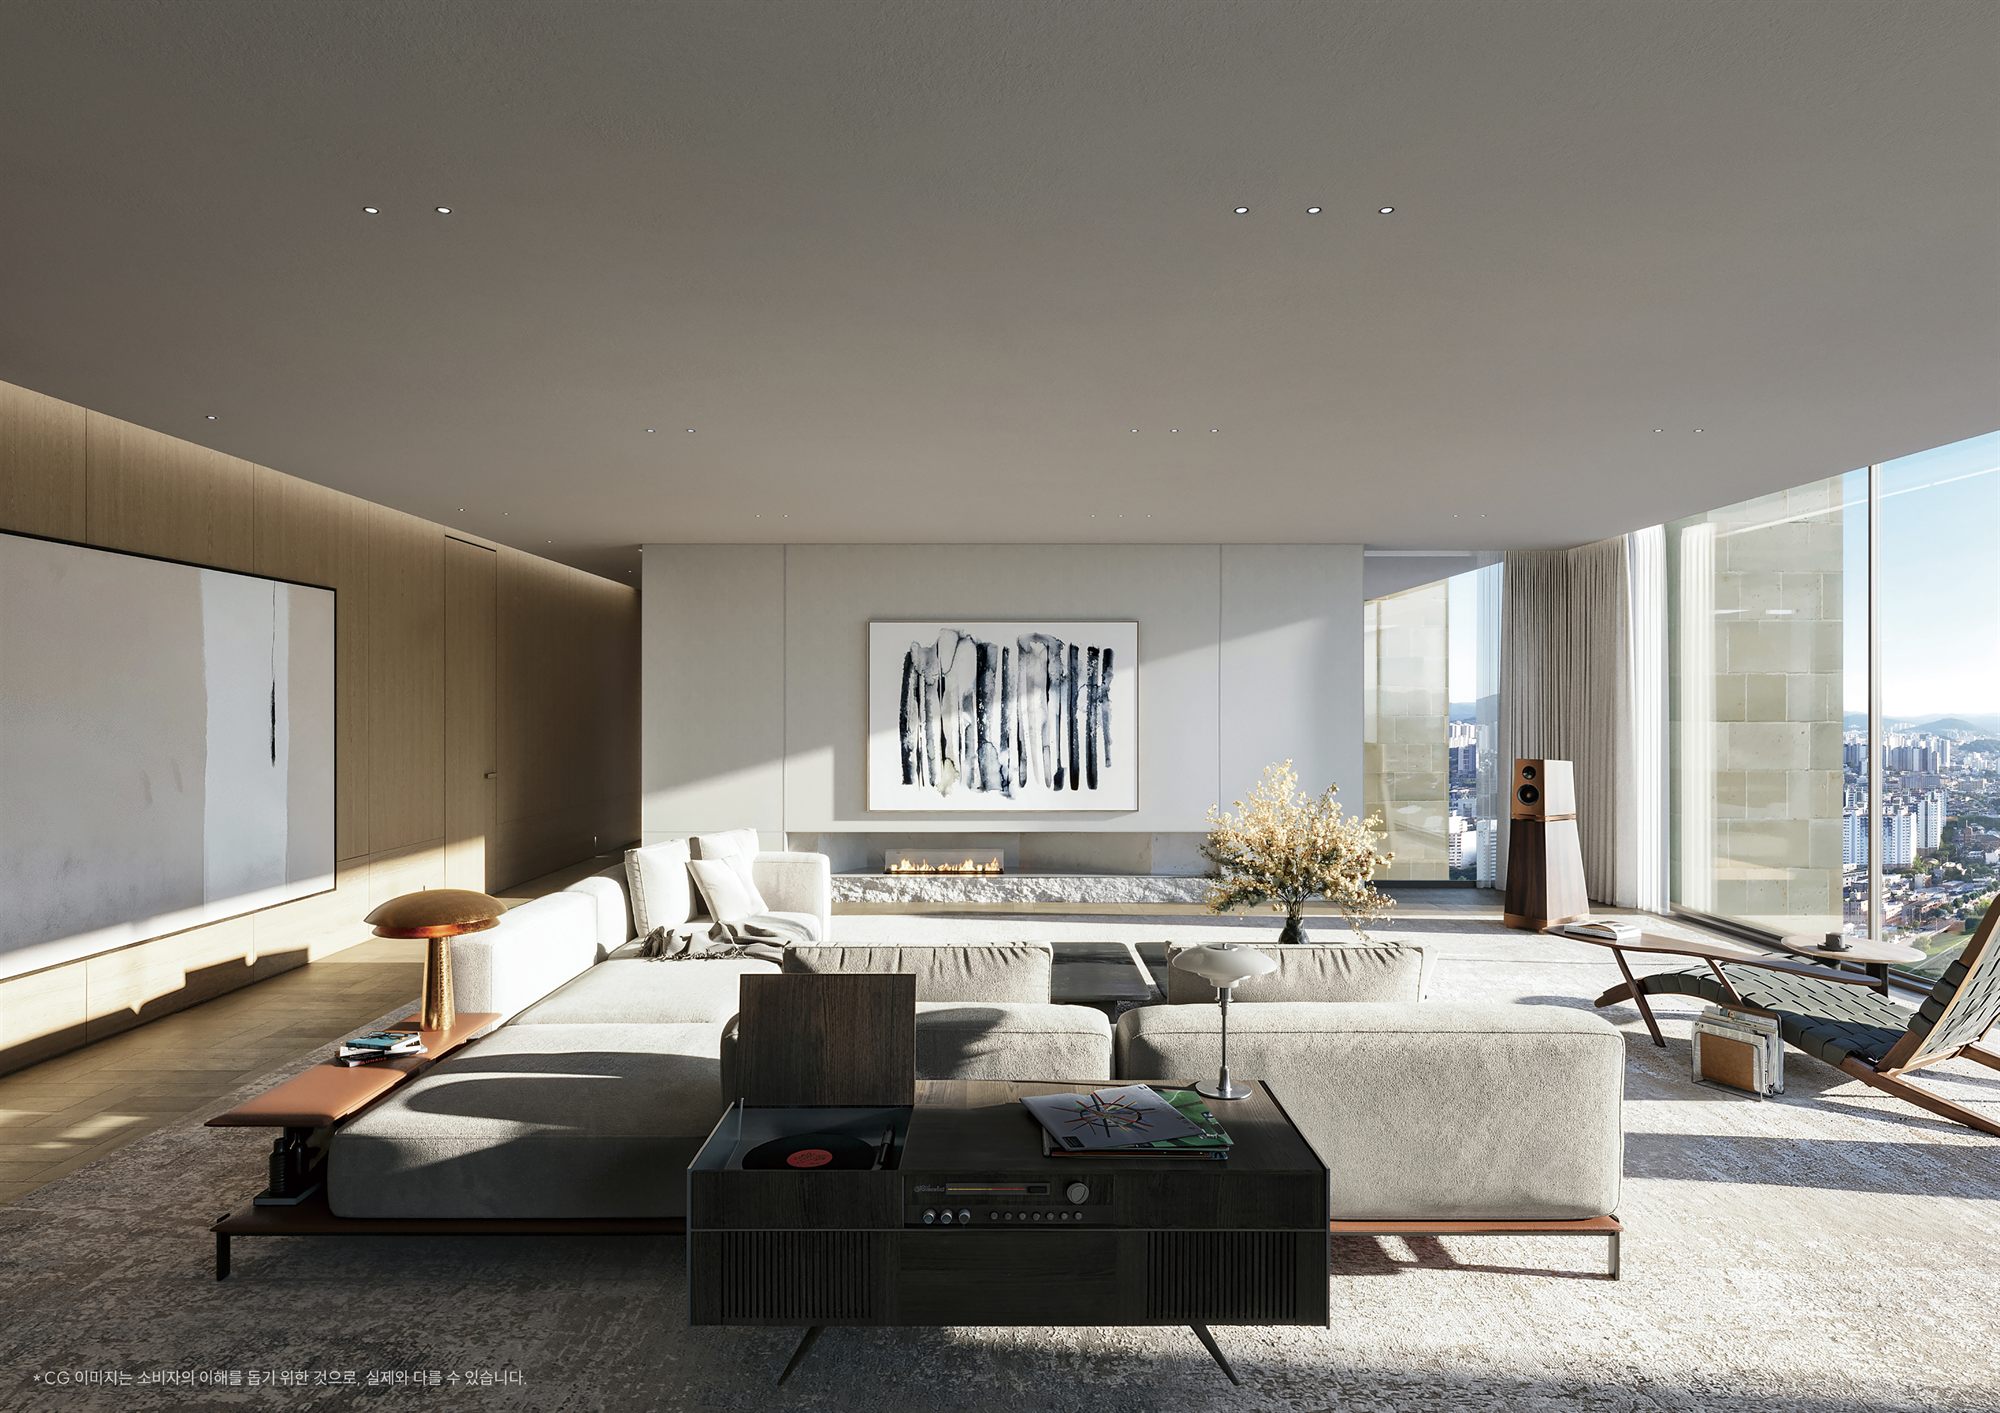
The shared proposal identifies the 74-pyeong exclusive plan as a four-room, 4.5-bath layout with two balconies, an alpha room, butler room, separate laundry and substantial dressing/storage areas. The plan should be attached to the contract with a final area schedule.
Commit in stages, verify at every gate.
Why Gangnam, Seocho and Yongsan command a premium
Seoul monitors the three Gangnam districts and Yongsan as a core high-price area, with nearby key districts tracked separately as the “Hangang belt.” River and park adjacency, central access and limited replacement supply concentrate demand and capital. Not everyone wants to live there—but the observed scarcity premium is real.
May 2026 year-on-year; Korea Real Estate Board data published by Seoul.
May 2026 year-on-year; the zone also includes Jongno and Jung.
May 2026 year-on-year; the zone also includes Songpa and Gangdong.
These are transaction-price index changes, not average sale prices and not projected returns for either project. The zone definitions are shown to avoid presenting multi-district statistics as Yongsan-, Gangnam- or Seocho-only results.
Views vary by unit; the wider geography creates a structural premium for limited supply.
BOK notes that self-funded transactions can sustain prime demand during credit tightening.
Rate, policy and redevelopment expectations can move demand before supply changes.
Policy has an effect—but not permanent control
Credit limits, permission zones and taxes can reduce leverage, transactions or the pace of gains. BOK research finds macroprudential tightening effective; it also finds that supply-demand, sentiment, economic conditions and interest rates jointly drive prices. Policy therefore moderates risk—it does not guarantee a lasting reversal of the prime-location premium.
Ultra-prime new-builds trade infrequently and can diverge sharply from apartment indices. Unit-specific comparables, contract assignability and buyer depth matter more.
The plan must pass the legislative process. The rule in force at each tax event, together with any transition provision, will control.
Policy can change Eterno’s economics before delivery.
Korean housing is both shelter and a major household investment asset. This section focuses on the new tax proposal and how owner occupancy, value and timing could affect a 2029-delivery purchase; the broader price and policy evidence is set out in Section 05.
We have a commercial interest in completing a transaction. That does not remove the buyer’s policy risk. Eterno’s stated October 2029 delivery falls in the same year that the proposal’s residence-based capital-gains design would be fully phased in. A buyer should see that risk before paying the deposit and six-month installments—not after them.
The official Q&A says the reform is designed around tax fairness and a sustainable system, while housing supply and finance measures address market stability in parallel.
The proposal favors qualifying owner-occupied one-home households and removes part of the tax advantage for high-value or non-owner-occupied housing.
A proposal is a risk input, not a deadline tactic or a prediction that Seoul prices will rise or fall.
Residence, value and timing become more important.
These are the provisions most relevant to an ultra-high-value home with planned delivery in 2029. Amounts refer to official value or statutory deductions—not the Eterno contract price itself.
Owner occupancy changes the deduction.
For a qualifying one-household/one-home owner, the proposed taxpayer threshold becomes KRW 1.4bn of official value. Once taxable, the basic deduction would be KRW 1.4bn for an owner-occupied home but KRW 0.9bn for a home the owner does not occupy.
Time held no longer substitutes for time lived there.
The one-home comprehensive holding-tax credit would move from holding period to actual residence period, with a proposed annual credit cap of KRW 6m from 2028.
The long-term deduction becomes residence-led.
For a qualifying one-home sale, the proposal moves to an 8%-per-year residence deduction, up to 80%, with a KRW 1.0bn annual per-person deduction cap from 2029. A non-owner-occupied home would not earn that residence-period deduction.
Not legally limited to three districts.
The formula is based principally on value, home count and occupancy—not a tax boundary naming Gangnam, Seocho and Yongsan alone. Its economic impact is nevertheless concentrated in high-priced Gangnam and the Hangang-belt markets, including Yongsan; “pinpoint increase” is a media characterization, not the statute’s map.
Primary source: Ministry of Finance and Economy, 2026 Tax Reform Plan and Q&A, announced 3 August 2026. Market characterization: Hankyoreh, 4 August 2026. Market dynamics: Bank of Korea housing-price expectations issue note.
Re-test the tax position at every contractual gate.
The proposal is relevant because the contract runs across several future tax years. It does not establish the buyer’s final bill today, and it should not be used to create artificial urgency.
What the evidence supports
Rules can change leverage, transaction volume and after-tax economics during a multi-year contract. They are material to the buyer’s plan, but they are not a reliable one-way forecast of the property’s 2029 market value.
What we will not claim
It is too simplistic to say taxes failed only because sellers raised asking prices by more than the tax. Asking prices are not completed transactions, and that statement does not isolate supply, credit, income, liquidity, redevelopment expectations or policy timing.
The proposal does not make the deposit itself an annual holding-tax event. Presale-right and assignment rules require a separate review.
If enacted unchanged, the fully phased residence-based design may be relevant after acquisition. Corporate ownership follows a different framework.
Recalculate under the law then in force; future administrations, legislation, court decisions or transition rules may change the result.
The Korean proposal’s residence period generally follows move-in records, subject to actual facts and limited exceptions for work, study, medical care and similar unavoidable moves. Before deposit, obtain a written Korean tax opinion for the exact purchaser and intended use.
A practical path for a foreign buyer
Foreign ownership is possible in Korea, but the route is document-heavy and, for homes in Seoul, currently shaped by special permission and actual-use rules. Treat the steps below as a workflow for counsel—not legal or tax advice.
Buyer & use classification
Confirm individual vs. entity, nationality, visa/residence plan, and whether the unit is legally a home or officetel. These facts change the permit, tax and financing analysis.
Land-transaction permission
Seoul has been subject to special foreign-buyer permission measures for residential purchases. Confirm that the designation is still effective on signing, whether this specific unit falls within it, and the actual-residence obligation.
Contract & reporting
Use a bilingual contract or a controlled translation. Real-estate transaction reporting and separate foreign-acquisition reporting may apply on statutory timelines.
Funds & banking trail
Pre-clear the remitting bank, source-of-funds evidence, Korean receiving account, FX reporting and anti-money-laundering review before any deposit deadline.
Tax & registration
Model acquisition and registration costs, annual holding taxes, rental/VAT treatment where relevant, and capital-gains exposure. Register title in the beneficial owner’s actual name.
Final inspection & closing
Tie the final payment to completion evidence, defect inspection, title and encumbrance checks, occupancy approvals, management rules and agreed deliverables.
Apartment vs. officetel
An apartment is housing by legal design. An officetel is a quasi-housing/business building that is commonly occupied as a home, but Korean tax authorities can look to actual use. Residential use can bring housing property tax and housing-count consequences; genuine business use can bring VAT and different land/building taxation.
Personal vs. entity ownership
A company can legitimately use or lease an officetel as an office, but incorporation is not a tax shortcut. A corporate purchase of residential housing can face higher acquisition and comprehensive holding-tax treatment, no ordinary corporate housing deduction, and additional tax on exit. Purpose, actual use and beneficial ownership must match the records.
Residence and visas
Owning Korean real estate does not itself grant a visa or residence status. Conversely, a visa category may not satisfy every property-use or lender requirement. Immigration advice should run in parallel.
Tax layers
Budget beyond price: acquisition and registration, legal and brokerage costs, possible VAT for an officetel, annual property-related taxes, operating charges and capital-gains tax on exit. U.S. tax reporting should also be reviewed.
A controlled sale price is not a guaranteed resale profit.
Korea’s price-ceiling system can create a gap between an approved new-home price and nearby market prices, but it applies only to qualifying housing supplied under the Housing Act. Assignment restrictions, actual-residence duties, tax and project structure can prevent or consume the apparent arbitrage.
Is the product covered?
Confirm whether the exact unit is housing supplied under Housing Act Article 54 and whether the site is public land or a designated private-land price-ceiling area. An officetel is not automatically covered.
Can the contract be assigned?
Read the approved supply notice and contract for resale/assignment restrictions. A statutory or contractual prohibition can make a short-term sale impossible regardless of the expected gain.
Must the buyer occupy?
Certain Seoul-area price-ceiling homes carry an actual-residence period of up to five years, with entry generally required within three years from first occupancy availability.
Project-specific conclusion
Parkside’s Korean-apartment route is reported as a proposed 10-year private rental with later sale conversion under review, not an ordinary presale. Eterno is presented as 29 apartments plus four officetels; its permit and supply basis must be obtained before claiming price-ceiling or resale treatment.
KRW 20.0bn purchase → KRW 24.0bn sale → KRW 4.0bn taxable gain
Individual seller; completed residential home; no other Korean homes; no exemption, surcharge, long-term deduction, financing cost or deductible expense; local income tax shown at 10% of national tax. USD uses KRW 1,380/USD. This is education, not a tax quote.
The 2+ year calculation applies the current 45% top rate and KRW 65.94m progressive deduction to a KRW 4.0bn taxable base, then adds illustrative local income tax. Actual taxable gain starts with sale proceeds less acquisition basis and allowable expenses; residency, home count and rules on the sale date can materially change the result.
Annual property tax
Local property tax is assessed annually using official value and statutory ratios, not the headline purchase price. Standard housing rates are progressive; urban-area, local education and other components can apply.
Comprehensive holding tax
National comprehensive real-estate tax is layered above local property tax. Current NTS guidance uses KRW 900m of aggregate official housing value as the individual deduction, or KRW 1.2bn for a qualifying resident one-household/one-home owner; companies generally receive no housing deduction.
Officetel actual use
A residentially used officetel can be assessed as housing and enter comprehensive holding-tax analysis. Genuine office use is generally treated as a building plus its land; residential rent is VAT-exempt, while business-use rent is generally VAT-taxable.
Acquisition and corporate route
Budget acquisition tax, registration, bonds, legal fees and possible VAT before comparing ownership names. Corporate residential ownership can face substantially less favorable acquisition and annual-tax rules; model the exact buyer and use before signing.
Ask a Korean tax adviser to model individual resident, individual nonresident, Korean company and foreign company outcomes for apartment 102-901 and officetel 201, including U.S. reporting and treaty/foreign-tax-credit interaction.
FROM MILITARY BASE TO PUBLIC REALM
Yongsan Park is real—but still evolving.
The central U.S. military garrison has been returning to Korean control in stages. Parts are already temporarily open, including the Yongsan Children’s Garden and former officers’ quarters. The government continues to manage planning, return, remediation and public access.
For a buyer, the park is a powerful long-term adjacency. It is not a finished amenity with a fixed final boundary and completion date. Environmental remediation, phased returns and master-plan changes should remain in the risk register.
Potential view, air and public-realm premium—subject to exact unit orientation and future landscaping.
Established embassy, school, dining and expatriate networks in Itaewon and Hannam.
Access to the CBD, Gangnam, Yeouido and the wider Seoul metropolitan rail network.
What should happen next
Documents
- Title and land registry extracts
- Building/project permits and approvals
- Korean sale/lease contract and attachments
- English controlled translation
- Floor plan, area schedule and finish book
- Management rules and estimated charges
Commercial
- Price inclusions, options and VAT
- Deposit custody and refundability
- Full interim-payment schedule
- Assignment/resale restrictions
- Delay, default and termination rights
- Parking, storage and amenity rights
Buyer readiness
- Purchasing name and beneficial owner
- Nationality and residence/visa plan
- Source-of-funds package
- Bank and FX transfer route
- Korean and U.S. tax memos
- Local counsel and power of attorney
Do not choose between the projects until the exact Parkside apartment right and the complete Eterno payment/closing schedule are on the table.
Those two documents will reveal whether this is primarily a lifestyle decision, a capital-allocation decision, or both.
Source notes
- The Parkside Seoul — official project site
- Maeil Business Newspaper — reported Parkside 10-year rental / sale-conversion plan (28 May 2025)
- Eterno Yongsan — official project site
- First Corporation — existing project information
- MOLIT — foreign-buyer land-transaction permission measure (21 Aug 2025)
- MOLIT — Seoul foreign home transactions after the measure (12 Feb 2026)
- Korean law in English — Act on Report on Real Estate Transactions
- Housing Act — housing, multi-family housing and quasi-housing definitions
- Korean government Easy Law — apartment definition and housing types
- Act on Ownership and Management of Condominium Buildings — sectional ownership
- Special Act on Private Rental Housing — current definitions
- Bank of Korea — Financial Stability Report (December 2025)
- Bank of Korea — Housing price expectations issue note
- Bank of Korea — Effectiveness of macroprudential policy issue note (24 Nov 2025)
- Korea Real Estate Board — transaction price index
- Seoul Metropolitan Government — May 2026 apartment transaction-price index (22 Jul 2026)
- Seoul Metropolitan Government — core high-price and Hangang-belt market monitoring (18 Mar 2026)
- Ministry of Finance and Economy — 2026 Tax Reform Plan (announced 3 Aug 2026)
- Hankyoreh — analysis of proposed owner-occupied / non-owner-occupied housing tax changes (4 Aug 2026)
- MOLIT — Yongsan Park program
- National Tax Service — individual capital-gains tax rates
- Income Tax Act, Article 104 — current capital-gains rates
- National Tax Service — comprehensive real-estate holding tax
- Housing Act, Article 57 — price-ceiling scope
- Housing Act, Article 57-2 — actual-residence obligations
- National Tax Service — officetel VAT and actual-use guidance
- Bank of Korea — daily interest-rate and FX releases
Important limitations
This is an initial marketing and decision-support brief, not an appraisal, offering memorandum, legal opinion, tax opinion or promise of future value. Project facts marked with an asterisk are based on user/seller-provided information and require verification against current official sales materials and executed agreements. Laws and policy designations can change. Independent Korean legal, tax, banking and technical advice is required before commitment.